What Does Kam Financial & Realty, Inc. Mean?
Table of ContentsThe smart Trick of Kam Financial & Realty, Inc. That Nobody is DiscussingAll about Kam Financial & Realty, Inc.Kam Financial & Realty, Inc. Can Be Fun For EveryoneRumored Buzz on Kam Financial & Realty, Inc.Little Known Facts About Kam Financial & Realty, Inc..Fascination About Kam Financial & Realty, Inc.Some Known Details About Kam Financial & Realty, Inc.
Buying a home is a significant landmark in many individuals's lives. That doesn't indicate the process is clear to those individuals (california loan officer). The home purchasing procedure involves many actions and variables, indicating everyone's experience will be unique to their household, economic situation, and desired property. Yet that does not indicate we can't help make feeling of the mortgage procedure.A is a type of funding you use to purchase residential or commercial property, such as a home. Typically, a loan provider will certainly give you a collection quantity of money based on the worth of the home you desire to get or own.
5 Simple Techniques For Kam Financial & Realty, Inc.
To receive a home loan, you will need to be a minimum of 18 years of ages. Factors that help in the home loan process are a reliable earnings source, a strong credit rating, and a small debt-to-income proportion. (https://pagespeed.web.dev/analysis/https-www-ghwickser-com/dlsby2bhkc?form_factor=mobile). You'll discover more concerning these consider Module 2: A is when the homeowner obtains a brand-new mortgage to replace the one they currently have in place
A functions likewise to an initial home loan. A runs a bit in a different way from a traditional mortgage financing and is similar to a credit history card.
This co-signer will accept make settlements on the home loan if the consumer does not pay as concurred. Title companies play a crucial function making certain the smooth transfer of residential property possession. They research state and county documents to validate the "title", or possession of the house being acquired, is free and free from any kind of various other mortgages or responsibilities.
Top Guidelines Of Kam Financial & Realty, Inc.
Additionally, they provide written assurance to the lending institution and develop all the documentation needed for the home loan. A deposit is the quantity of money you need to pay in advance towards the purchase of your home. If you are acquiring a home for $100,000 the loan provider may ask you for a down settlement of 5%, which indicates you would be required to have $5,000 in cash money as the down repayment to buy the home. (https://calendly.com/luperector-proton/30min).
Many lending institutions have traditional home mortgage guidelines that allow you to borrow a specific percent of the worth of the home. The percentage of principal you can borrow will vary based on the home mortgage program you qualify for.
There are unique programs for first-time home customers, veterans, and low-income customers that allow reduced down payments and greater portions of principal. A mortgage banker can evaluate these choices with you to see if you qualify at the time of application. Rate of interest is what the loan provider costs you to obtain the cash to buy the home.
Kam Financial & Realty, Inc. Can Be Fun For Anyone
If you were to secure a 30-year (360 months) home loan and borrow that same $95,000 from the above example, the complete amount of interest you would certainly pay, if you made all 360 month-to-month payments, would certainly be a little over $32,000. Your month-to-month payment for this loan would certainly be $632.
When you have a home or building you will have to pay building taxes to the county where the home lies. Many lenders will certainly require you to pay your taxes with your home mortgage repayment. Real estate tax on a $100,000 car loan could be around $1,000 a year. The lending institution will certainly separate the $1,000 by one year and include it to your repayment.
The Facts About Kam Financial & Realty, Inc. Uncovered
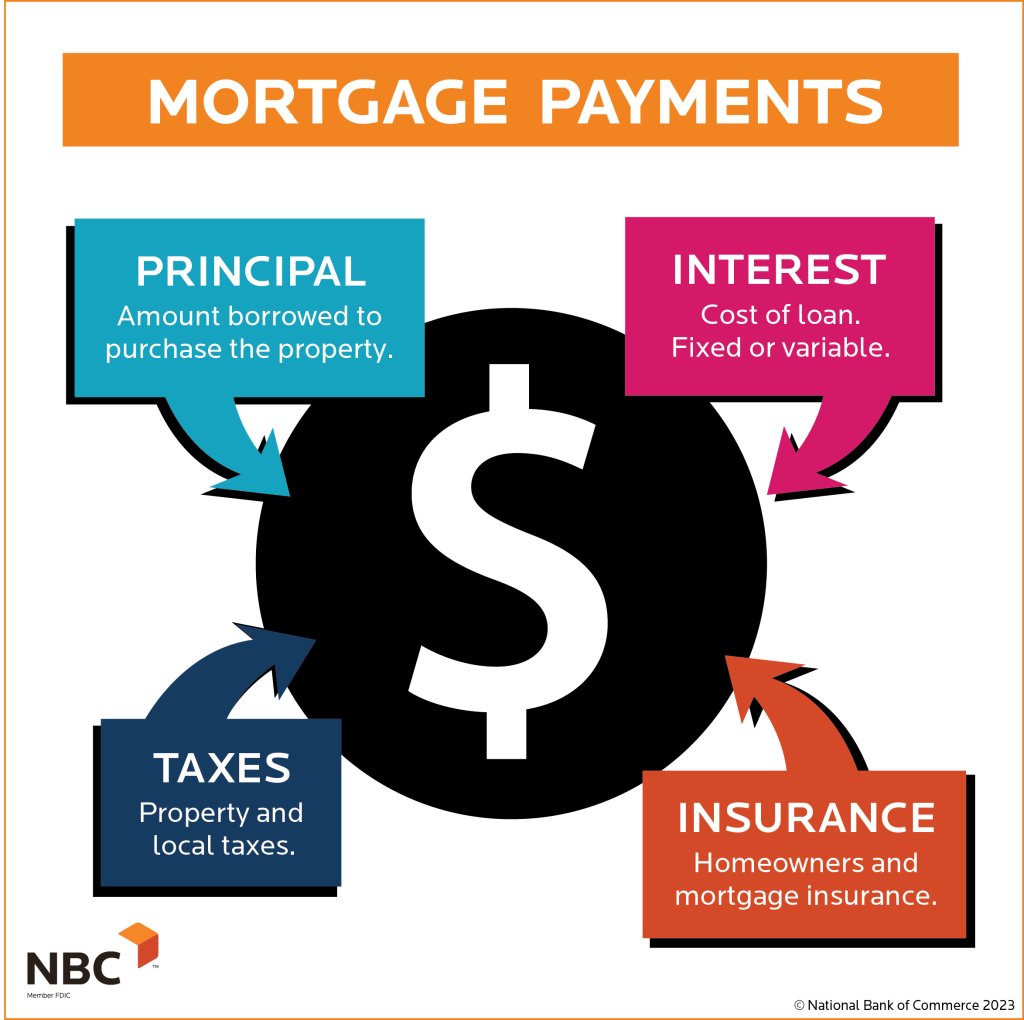
Once again, because the home is seen as collateral by the lender, they desire to make sure it's shielded. Like taxes, the lender will also offeror often requireyou to include your insurance coverage costs in your month-to-month repayment.
Your settlement currently would increase by $100 to a new overall of $815.33$600 in concept, $32 in rate of interest, $83.33 in tax obligations, and $100 in insurance coverage. The lender holds this cash in the exact same escrow account as your residential property taxes and pays to the insurer on your part. Closing costs describe the costs connected with refining your financing.
The 30-Second Trick For Kam Financial & Realty, Inc.
This guarantees you comprehend the overall cost and consent to continue before the loan is funded. There are various programs and loan providers you can pick from when you're purchasing a home and obtaining a home mortgage that can help you navigate what programs or choices will certainly work best for you.
Unknown Facts About Kam Financial & Realty, Inc.
Many economic institutions and real estate agents can help you understand exactly how much money you can invest on a home and what lending quantity you will get. Do some study, however also request for recommendations from your family and friends. Locating the appropriate companions that are a great suitable for you can make all the difference.